Thursday, January 2, 2025

6 important information you should provide about your life insurance beneficiary


Life insurance provides financial protection for your loved ones in the event of your untimely death. When you purchase a life insurance policy, you will be required to name a beneficiary who will receive the death benefit payout in the event of your passing. Choosing the right beneficiary and providing the necessary information is crucial to ensuring that your loved ones receive the benefits they are entitled to.

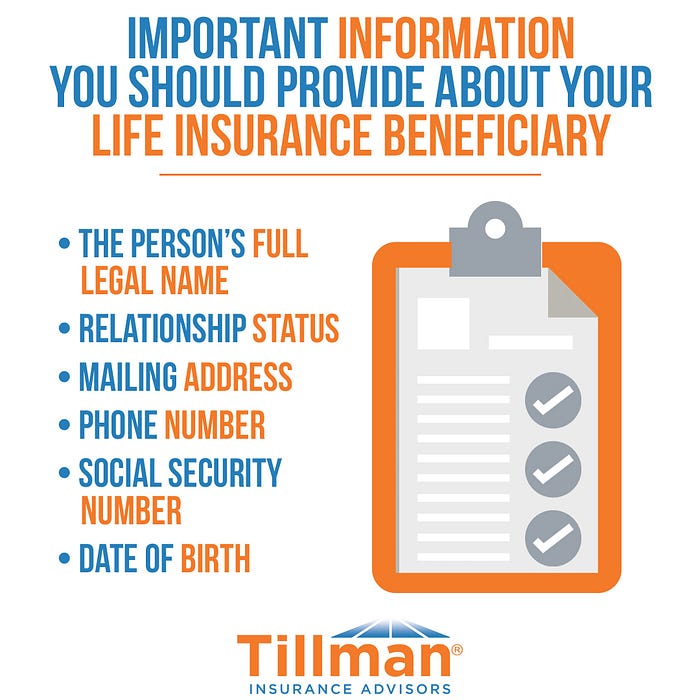
Here are six important pieces of information you should provide about your life insurance beneficiary:

  1. Full legal name:
    When naming your life insurance beneficiary, it’s essential to provide their full legal name. This includes their first, middle, and last name. Providing the full legal name ensures that there is no confusion when it comes time for the insurance company to pay out the death benefit.
  2. Relationship to you:
    It’s important to specify your beneficiary’s relationship to you. This can include a spouse, child, parent, or other family member. If you choose someone who is not a family member, such as a friend or a charity, make sure to specify their relationship to you.
  3. Contact information:
    You should provide your beneficiary’s current contact information, including their address, phone number, and email address. This will enable the insurance company to contact them quickly and easily in the event of your passing.
  4. Social Security number:
    Providing your beneficiary’s Social Security number is essential to ensure that there is no confusion about their identity. This information can help the insurance company accurately identify your beneficiary and locate them quickly.
  5. Contingent beneficiary:
    It’s important to name a contingent beneficiary who will receive the death benefit payout if your primary beneficiary predeceases you or is otherwise unable to receive the benefits. You should provide the same information for your contingent beneficiary as you do for your primary beneficiary, including their full legal name, relationship to you, contact information, and Social Security number.
  6. Special instructions:
    If you have any special instructions or wishes for how the death benefit payout should be used, it’s essential to communicate this information to your beneficiary. This can include instructions
    for paying off debts, providing for children’s education, or donating to a charity. By communicating your wishes to your beneficiary, you can ensure that your death benefit payout is used in a way that aligns with your values and priorities.

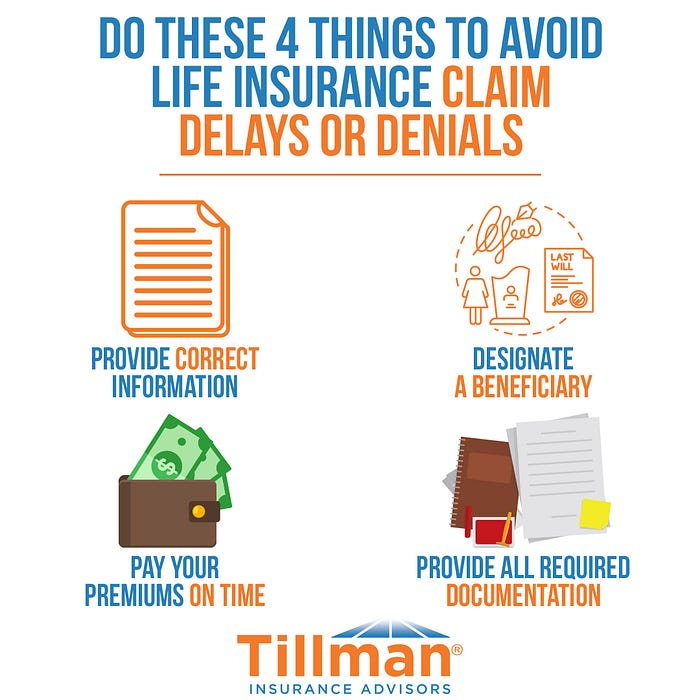
In conclusion, providing accurate and complete information about your life insurance beneficiary is crucial to ensure that your loved ones receive the benefits they are entitled to. By providing your beneficiary’s full legal name, specifying their relationship to you, providing contact information, and Social Security number, you can help the insurance company identify and locate your beneficiary quickly. Naming a contingent beneficiary can also ensure that your death benefit payout goes to the right person if your primary beneficiary is unable to receive the benefits. Additionally, communicating any special instructions or wishes can help ensure that your death benefit payout is used in a way that aligns with your values and priorities.

Monday, December 30, 2024

5 steps to filing a claim as a life insurance policy beneficiary


Losing a loved one is a difficult and emotional time, and having to file a life insurance claim can add to the stress. However, filing a claim as a life insurance policy beneficiary doesn’t have to be a complicated process. Here are five steps to help you file a claim and receive the benefits you’re entitled to:

Step 1: Gather the necessary documents
Before filing a claim, you’ll need to gather certain documents, including the policyholder’s death certificate and the original life insurance policy. You may also need to provide additional documentation, such as a copy of the policyholder’s will or trust.

Step 2: Contact the insurance company
Contact the insurance company to inform them of the policyholder’s death and to request a claim form. You may be able to obtain the form online or by calling the insurance company’s customer service department.

Step 3: Fill out the claim form
Complete the claim form and provide any necessary documentation, such as the death certificate and policy documents. Make sure to provide accurate and detailed information to avoid any delays in the claims process.

Step 4: Submit the claim form
Submit the claim form and required documentation to the insurance company. You may be able to submit the claim form online, by mail, or by fax. It’s important to follow the insurance company’s instructions carefully to ensure that your claim is processed in a timely manner.

Step 5: Follow up with the insurance company
After submitting your claim, follow up with the insurance company to ensure that it’s being processed. You may need to provide additional information or answer questions about the claim. Once the claim is approved, you should receive the benefit payout.

In conclusion, filing a life insurance claim can seem overwhelming, but by following these five steps, you can help ensure that the process goes smoothly and that you receive the benefits you’re entitled to as a policy beneficiary. Remember to gather the necessary documents, contact the insurance company, fill out and submit the claim form, and follow up with the insurance company until the claim is processed.

Monday, December 2, 2024

Car insurance trends in 2024: what drivers need to know

The auto insurance landscape is constantly evolving. As we move toward 2024, several trends are affecting premiums, coverage and driving habits. Staying informed about these topics can help you make smarter insurance decisions.

1. Increased premiums

One of the most important trends is the increase in auto insurance premiums. Inflation and rising vehicle repair costs are driving up insurance rates. Advanced technology in automobiles (such as cameras and reversing sensors) will make driving safer, but it also makes repairs more expensive, pushing insurers to raise prices. Be sure to review your policy annually and ask for discounts to help offset rising costs. Combine your policy with your home's whenever you can.

2. Distracted driving

Distracted driving remains one of the leading causes of accidents, and texting and in-car entertainment are the main culprits. Many insurers now offer telematics programs that track your driving behavior and reward safe drivers with discounts. Enrolling in these programs can help reduce your premiums and, at the same time, promote road safety.

3. Electric vehicle (EV) insurance

With more electric vehicles (EVs) in circulation, drivers face new insurance challenges. While some insurers offer discounts for EVs due to their environmental benefits, the cost of repairs is usually higher. Specialized parts and fewer repair shops mean that EV owners must compare policies tailored to their specific needs. Keep this in mind when buying a new car.

more Info : Car insurance quote in Charlotte

Wednesday, November 27, 2024

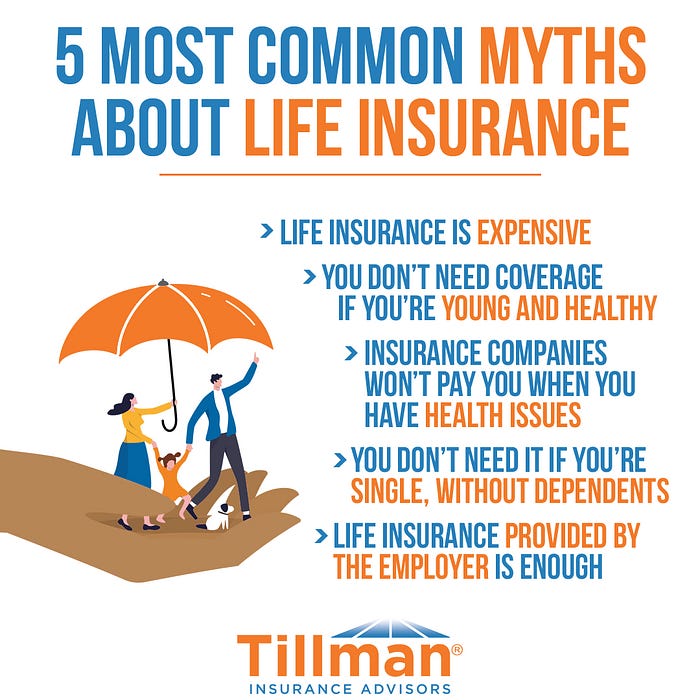
5 most common myths about life insurance


When it comes to life insurance, there are many myths and misconceptions that can prevent people from purchasing the coverage they need. Life insurance is a crucial component of financial planning, and it’s important to separate fact from fiction when making decisions about your coverage.

In this article, we will debunk five of the most common myths about life insurance.

Myth #1: Life insurance is only for people with dependents
While life insurance is often associated with providing for dependents in the event of a policyholder’s death, it can also serve other purposes. For example, life insurance can be used to pay off debts, cover funeral expenses, or provide an inheritance for loved ones.

Myth #2: Life insurance is too expensive
Life insurance can be surprisingly affordable, especially for younger and healthier individuals. Term life insurance policies, in particular, can provide significant coverage at a low cost.

Myth #3: My employer-provided life insurance is enough
Employer-provided life insurance policies often have low coverage limits and may not meet your financial needs. Additionally, if you leave your job, you may lose your coverage.

Myth #4: I don’t need life insurance because I’m young and healthy
Unfortunately, unexpected events can happen at any age. Life insurance provides financial protection for your loved ones in the event of your unexpected death, regardless of your age or health status.

Myth #5: I don’t need life insurance because I have no debt
While it’s true that life insurance can be used to pay off debts, it can also provide financial protection for your loved ones in other ways. For example, life insurance can help cover funeral expenses or provide an inheritance for your loved ones.

In conclusion, life insurance is a crucial component of financial planning, but there are many myths and misconceptions that can prevent people from purchasing the coverage they need. By separating fact from fiction, you can make informed decisions about your life insurance coverage and ensure that you and your loved ones are protected in the event of the unexpected.

Thursday, November 21, 2024

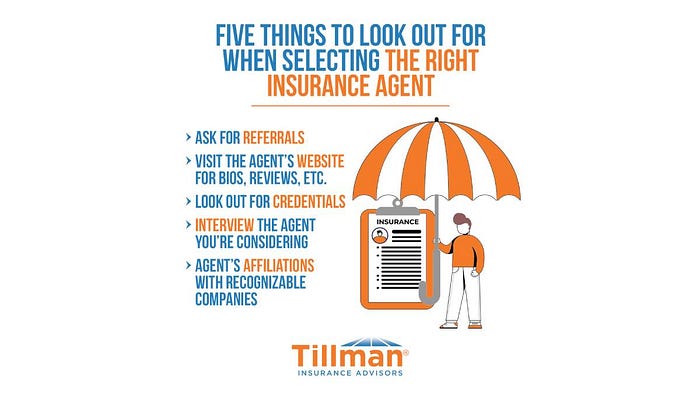
Things to look out for when selecting the right insurance agent


Selecting the right insurance agent is an important decision when purchasing life insurance. An agent can help you avigate the complex world of insurance policies and make informed decisions about coverage.

Here are some things to look out for when selecting the right insurance agent:

  • Credentials and experience
    The first thing to look for in an insurance agent is their credentials and experience. Check that the agent is licensed and authorized to sell life insurance in your state. Additionally, look for an agent who has experience selling life insurance policies and has a good track record of customer satisfaction.
  • Understanding of your needs
    A good insurance agent will take the time to understand your specific needs and circumstances. They should ask detailed questions about your financial situation, dependents, and future plans to help determine the appropriate coverage for your needs. Look for an agent who takes the time to get to know you and your unique situation.
  • Product offerings
    Different insurance agents may offer different types of policies and coverage options. Look for an agent who offers the type of coverage you need, and who can explain the different policy options and features in a clear and understandable way. They should be able to help you choose the right policy for your needs and budget.
  • Customer service
    Customer service is an important factor to consider when selecting an insurance agent. Look for an agent who is responsive to your needs and concerns, and who is available to answer your questions and address any issues that may arise. They should be easy to reach by phone or email and should provide timely and helpful responses.
  • Reputation
    The reputation of an insurance agent can be a good indicator of their level of service and expertise. Look for an agent who has a good track record of customer satisfaction, and who has positive reviews from current and former clients. You can check online review sites and industry organizations to get a sense of the agent’s reputation.
  • Transparency
    Finally, look for an insurance agent who is transparent about the policies they are selling and the commission they receive. They should be upfront about any fees or charges associated with the policy, and should provide clear and detailed information about the policy’s terms and conditions. They should also be transparent about the commission they receive from the sale of the policy.

Selecting the right insurance agent is an important part of the life insurance buying process. By looking for an agent with the appropriate credentials and experience, a good understanding of your needs, and a reputation for customer service and transparency, you can make an informed decision and choose an agent who will work with you to provide the right coverage for your needs.

Read more About:- Health Insurance Advisors in Charlotte

Monday, November 18, 2024

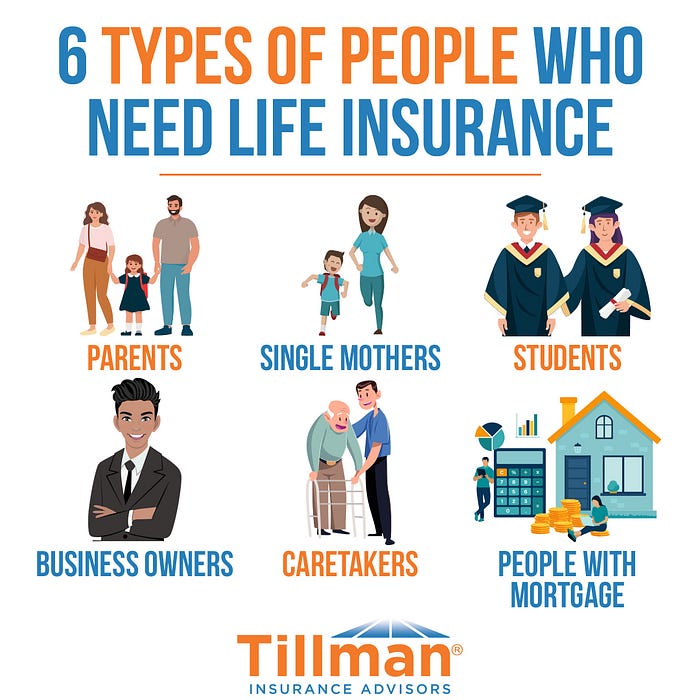
6 types of people who need life insurance


Life insurance is an important financial product that provides a safety net for your loved ones in the event of your unexpected death. Here are six types of people who may benefit from having life insurance:

  1. Parents with dependents: Parents with dependents, such as children or elderly parents, have a responsibility to provide for their loved ones in the event of their unexpected death. Life insurance can help ensure that their dependents have the financial resources they need to cover expenses such as childcare, education, and household bills.
  2. Newlyweds: Newlyweds may not immediately think about life insurance, but it can be an important investment for their future. If one spouse were to die unexpectedly, the other spouse would be left with the financial burden of funeral expenses, outstanding debts, and other costs. Life insurance can provide a safety net for the surviving spouse.
  3. Business owners: Business owners have unique financial responsibilities that may require life insurance coverage.
    Business owners may use life insurance to fund a buy-sell agreement, to provide key person coverage for important employees, or to provide a safety net for the business in the event of the owner’s unexpected death.
  4. Homeowners with mortgages: Homeowners with mortgages may benefit from having life insurance to cover the remaining balance of their mortgage in the event of their death. This can help ensure that their loved ones are not burdened with mortgage payments after they are gone.
  5. Single parents: Single parents have the sole responsibility of providing for their children. Life insurance can provide a safety net for their children in the event of the parent’s unexpected death. This can help ensure that their children are provided for financially and can continue to receive the care they need.
  6. Retirees: Retirees may not immediately think of life insurance as a necessary investment, but it can be an important part of their estate planning. Life insurance can provide a safety net for their loved ones in the event of their death, and can help cover final expenses and outstanding debts.

In conclusion, life insurance can provide financial security and peace of mind for a variety of people in different life situations. Whether you are a parent with dependents, a newlywed, a business owner, a homeowner with a mortgage, a single parent, or a retiree, life insurance can provide a safety net for your loved ones and protect your financial future.

Wednesday, October 9, 2024

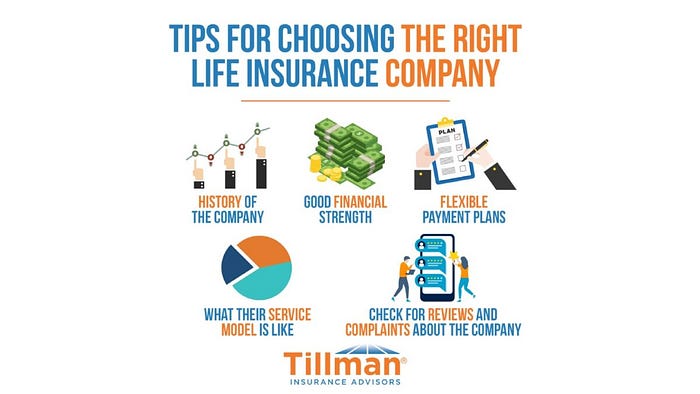
Tips for choosing the right life insurance company


Life insurance is an essential financial product that provides a safety net for your loved ones in the event of your unexpected death. Choosing the right life insurance company is an important decision, as it can impact your financial security and peace of mind. Here are some tips to help you select the right life insurance company for your needs:

  1. Research the company’s financial stability
    One of the most important factors to consider when selecting a life insurance company is its financial stability. Look for a company that has a strong financial rating from a reputable rating agency, such as A.M. Best, Moody’s, or Standard & Poor’s. You can typically find this information on the company’s website or by doing a quick online search. A financially stable company will be better able to pay out claims and honor its policy obligations.
  2. Consider the company’s reputation
    Another important factor to consider is the company’s reputation. Look for a company that has a good track record of customer service and satisfaction. Read reviews from current and former policyholders, and check with consumer advocacy groups such as the Better Business Bureau to see if any complaints have been lodged against the company.
  3. Evaluate the company’s product offerings
    Different life insurance companies offer different types of policies and coverage options. Evaluate the company’s product offerings to determine if they offer the type of coverage you need. Consider the policy’s premiums, death benefit amount, and any additional benefits or riders that may be available.
  4. Compare premiums from multiple companies
    Life insurance premiums can vary widely between companies, so it’s important to compare quotes from multiple providers. You can do this by working with an independent insurance agent or by using an online quote comparison tool. Be sure to compare apples to apples by comparing policies with similar coverage amounts and terms.
  5. Look for additional benefits and features
    Some life insurance companies offer additional benefits and features, such as accelerated death benefits, which allow policyholders to access a portion of their death benefit early if they are diagnosed with a terminal illness. Look for a company that offers these types of additional benefits, as they can provide added value and peace of mind. Consider the company’s underwriting process Finally,
  6. Consider the company’s underwriting process.
    This is the process by which the company evaluates your risk and determines your premium rate. Look for a company that has a fair and transparent underwriting process, and be prepared to provide accurate and detailed information about your health and lifestyle. Choosing the right life insurance company is an important decision that can impact your financial security and peace of mind. By researching the company’s financial stability and reputation, evaluating its product offerings and premiums, and considering any additional benefits and features, you can make an informed decision and select a life insurance provider that meets your needs.

Insurance Companies in Charlotte, NC: How to Choose the Right Insurance Agency

  When you’re searching for insurance companies in Charlotte NC, you may quickly realize that there are many options to choose from. With so...